Retirement is often treated like a switch: one Friday you are working, and by Monday your calendar belongs entirely to you.
But that sudden freedom can also remove income, routine, workplace friendships, professional identity, and familiar responsibilities at exactly the same time.
William chose a different route. Instead of leaving full-time work overnight, he gradually reduced his schedule over three years.
What surprised him was that phased retirement changed far more than his paycheck. It became a rehearsal for the financial, social, and emotional realities of life after work.
What William’s Three-Year Retirement Transition Looked Like
For illustration, assume William originally worked about 40 hours across five days. In his first transition year he moved to four days, then three days, then roughly two days before leaving completely.
That first move alone was larger than it looked. Going from five workdays to four creates roughly 52 additional weekdays a year, or about 416 hours, before accounting for vacations and holidays.
| Stage | Approximate Schedule | Work Time vs. Full-Time | Main Goal |
|---|---|---|---|
| Before transition | 5 days a week | 100% | Build retirement readiness |
| Year 1 | 4 days a week | About 80% | Test extra free time |
| Year 2 | 3 days a week | About 60% | Build a retirement routine |
| Year 3 | 2 days a week | About 40% | Practice living mostly retired |
| Full retirement | No regular job schedule | 0% | Replace work with chosen structure |
The important part was not the exact schedule. It was that William had several opportunities to discover what needed fixing while employment income and familiar routines were still partly available.
Research using U.S. Health and Retirement Study data has found associations between phased retirement and better financial and psychological outcomes compared with moving directly from full-time work into complete retirement, although individual circumstances vary substantially.
1. An Extra Day Off Felt Bigger Than a 20% Cut in Work
William expected four workdays instead of five to feel like a small adjustment. Instead, the extra weekday changed the rhythm of the entire week.
Appointments stopped consuming evenings. Errands could happen when stores were quiet, exercise no longer had to be squeezed around commuting, and a short trip no longer required sacrificing most of his weekend.
That taught him an important lesson about retirement planning. Time does not always increase in proportion to the hours removed from work because one completely free day can be more useful than several scattered free evenings.
The tradeoff, of course, was compensation. Someone considering the same move needs to compare the value of regained time with reduced wages, retirement-plan contributions, employer benefits, bonuses, pension accrual, and future Social Security earnings.
2. He Did Not Automatically Know What to Do With Free Time
William had spent years imagining how pleasant an empty Tuesday would feel. Once Tuesdays became empty every week, he learned that freedom and fulfillment were not the same thing.
The first few were wonderful. After that, household chores quietly expanded to occupy whatever time he gave them, and afternoons could disappear into television, internet browsing, errands, and tasks he would barely remember afterward.
Research on retirement transitions has found that paid work provides more than income. It can supply time structure, social interaction, identity, purpose, and regular activity, all of which may need replacements after work ends.
William therefore began treating free time as something to design rather than consume. He scheduled exercise, lunch with friends, home projects, reading, volunteering, and genuinely empty periods instead of expecting a satisfying retirement routine to appear automatically.
3. Workplace Friendships Changed Before He Actually Retired
William expected to miss coworkers after retirement. He did not expect those relationships to begin changing while he was still technically employed.
Once he stopped being present five days a week, he missed small conversations, spontaneous lunches, inside jokes, and decisions made on days he was absent. Nobody had deliberately excluded him, but he was no longer participating in every ordinary moment that made the workplace feel like a community.
Retirement research has found that some of the more peripheral social relationships people maintain through work decline around the retirement transition, even when close relationships remain intact.
That gave William time to strengthen relationships outside work before he depended on them. He stopped counting casual workplace contact as his entire social life and became more deliberate about seeing neighbors, relatives, old friends, and people connected to hobbies.
| What Work Quietly Provided | What Could Replace It | What William Learned |
|---|---|---|
| Daily conversation | Friends, clubs, volunteering | Social contact needs planning |
| Fixed schedule | Personal weekly routine | Freedom still benefits from structure |
| Professional identity | Hobbies, family roles, community work | Identity can become broader |
| Problems to solve | Projects, learning, mentoring | Mental challenge does not have to end |
| Sense of contribution | Volunteering or helping others | Purpose matters beyond a paycheck |
The table also explains why retirement can feel strangely empty even when finances are solid. A retirement portfolio can replace salary, but it cannot automatically replace everything the workplace was providing.
4. Spending Less Was Easier When the Change Happened Gradually
William assumed reduced working hours would make every spending decision feel restrictive. Instead, spending adjusted more naturally than he expected because several work-related expenses fell at the same time.
There were fewer commuting days, fewer purchased lunches, less convenience spending, and less temptation to reward himself after exhausting weeks. He also discovered that having more time occasionally let him choose less expensive options rather than paying for speed and convenience.
That did not mean phased retirement automatically saved money. Travel, hobbies, dining out, home improvements, and family support could easily use the money freed elsewhere.
The useful lesson was that William could observe his real retirement-style spending while still receiving employment income. Instead of building a retirement budget entirely from estimates, he gradually collected evidence about how he actually behaved when more of his time belonged to him.
5. Income Became Less Important Emotionally Before It Became Less Important Financially
The first reduction in William’s paycheck bothered him more than he expected. Even though the reduction was planned, seeing a smaller deposit created the uncomfortable feeling that he was moving backward.
By the second and third years, his perspective had changed. He began measuring the value of work partly in time rather than judging every decision by the size of his paycheck.
That distinction matters because people can be financially ready to reduce work while still being emotionally attached to maximum earnings. Others may desperately want fewer hours but genuinely need the income.
Phased retirement gave William time to separate those two questions. He could ask, “Do I still need this income?” separately from, “Am I uncomfortable giving this income up?”
6. He Learned Whether His Retirement Budget Worked Before Fully Depending on It
A spreadsheet can show whether projected income covers projected expenses. It cannot completely show how a household will react when earned income starts disappearing.
William used his reduced schedule as a financial rehearsal. As his paycheck decreased, he tried living closer to the amount he expected to spend after retirement rather than simply supplementing every reduction from savings.
This exposed categories he had underestimated and others he had overestimated. It also showed which discretionary expenses mattered enough that he did not want to eliminate them.
For someone considering phased retirement, the following test can be more useful than simply asking whether a portfolio has reached a certain balance.
| Area to Test | Stronger Position | Possible Warning Sign |
|---|---|---|
| Core expenses | Dependable income covers most essentials | Essentials require aggressive withdrawals |
| Cash reserve | Several unexpected bills can be absorbed | Every surprise requires selling investments |
| Debt | Payments are manageable | Debt consumes large share of retirement cash flow |
| Healthcare | Coverage transition understood | Coverage or enrollment dates remain unclear |
| Lifestyle spending | Real spending has been tracked | Retirement budget is based mostly on guesses |
| Social routine | Activities exist outside work | Nearly all contact still comes from coworkers |
No single row determines retirement readiness. The point is to expose weak areas before the final paycheck disappears rather than after.
7. Part-Time Work Required Stronger Boundaries Than Full-Time Work
William initially imagined that reducing his schedule would automatically reduce his workload. That did not happen immediately.
Meetings still appeared on days off. Email continued arriving. Coworkers occasionally treated his reduced schedule as four days of availability compressed into three.
He eventually realized that phased retirement works best when duties shrink along with hours. Otherwise, a worker can end up accepting part-time compensation while carrying nearly full-time responsibility.
That meant becoming clearer about what would no longer be his job. He transferred projects, documented processes, trained colleagues, and became less willing to rescue every issue simply because he knew how.
This surprised him because retirement preparation turned out to involve letting other people become capable without him. That process was uncomfortable at first, but it made the final departure much easier.
8. Becoming Less Essential Was Uncomfortable but Liberating
For years, William had taken pride in being the person people called when something complicated happened. During phased retirement, those calls became less frequent.
His first reaction was not relief. It was disappointment.
Over time, however, he understood that being needed at work was different from having value as a person. His employer’s ability to function without him was not evidence that his career had meant little; it was evidence that a transition had actually occurred.
This is one reason retirement identity deserves as much attention as retirement income. Work can become intertwined with status, usefulness, expertise, and belonging, and those parts of identity may take time to rebuild elsewhere.
Gradually stepping away gave William time to develop other answers to the question, “What do you do?” By his final year, his occupation had become one part of his history rather than the main description of his present life.
9. His Spouse Also Had to Adjust to His Retirement
William originally thought of retirement as his transition because he was the one leaving work. It quickly became obvious that his changing schedule affected the household as well.
An extra person at home changed quiet time, chores, meal routines, errands, travel planning, and expectations about what they would do together. Having more shared time did not automatically mean both people wanted to spend all of that time together.
The gradual transition gave them space to discover a healthier rhythm. They developed some activities they enjoyed together while protecting separate friendships, interests, and personal time.
That became one of William’s biggest surprises. A couple can spend decades preparing financially for retirement without discussing what an ordinary Wednesday afternoon will actually look like once both people are home.
10. Social Security and Retirement Were Two Separate Decisions
William had once thought leaving work and claiming Social Security would probably happen at roughly the same time. Phased retirement showed him that they were separate decisions.
Someone can reduce work, continue working part time, fully retire, and claim Social Security on different dates. For people born in 1960 or later, full retirement age is 67, while retirement benefits can generally begin as early as 62 at a permanently reduced monthly amount.
Working while receiving Social Security can also matter before full retirement age. In 2026, a beneficiary below full retirement age for the entire year can earn up to $24,480 before the retirement earnings test begins withholding benefits; SSA generally withholds $1 in benefits for every $2 earned above that amount.
For someone reaching full retirement age during 2026, the higher limit is $65,160 for earnings before the month full retirement age is reached, with $1 withheld for every $3 above the limit. Beginning with the month full retirement age is reached, the earnings test no longer reduces benefits based on earnings.
| 2026 Social Security Situation | Earnings-Test Rule | Why It Matters |
|---|---|---|
| Under FRA all year | $24,480 limit | Benefits may be withheld above limit |
| Reaches FRA during 2026 | $65,160 limit before FRA month | Higher temporary threshold applies |
| FRA reached | No earnings limit | Work earnings no longer trigger withholding |
| Born 1960 or later | FRA is 67 | Claiming at 62 can reduce worker benefit by up to 30% |
Amounts withheld under the earnings test are not necessarily lost in the same way as an ordinary tax or fee. SSA later recalculates benefits after full retirement age to account for months in which benefits were withheld because of excess earnings.
For William, the larger lesson was simply not to let a work-schedule decision accidentally make the Social Security decision for him.
11. Turning 65 Did Not Make Healthcare Decisions Automatic
Another surprise was that reaching age 65 did not create one universal Medicare answer for someone still working. The correct enrollment timing can depend on current employer coverage, the employer’s size, whether coverage is based on current employment, HSA considerations, and other circumstances.
Medicare says people who remain covered through their own or a spouse’s current employment may, in qualifying circumstances, delay Part B without a late-enrollment penalty. When employment or qualifying job-based coverage ends, an eight-month Special Enrollment Period may be available for Part B.
That made healthcare one of the areas William refused to handle casually. He confirmed how his employer coverage coordinated with Medicare before reducing hours or assuming a later enrollment date would be harmless.
This matters especially because reducing hours can sometimes affect eligibility for employer health benefits. A phased-retirement agreement that looks attractive based only on salary could become much less attractive if it unexpectedly changes health insurance.
12. Hobbies Became Satisfying Only After He Started Taking Them Seriously
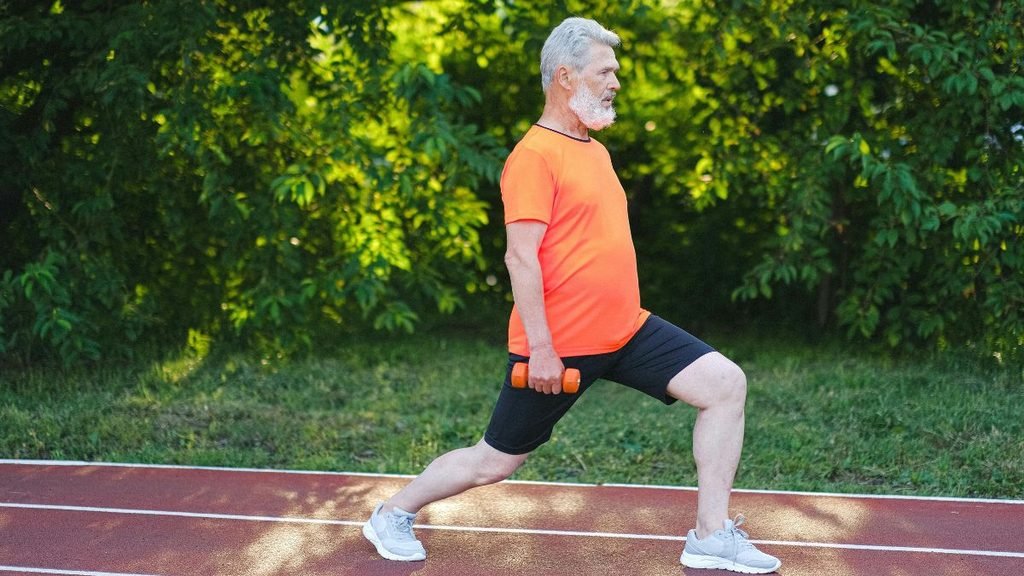
William had a familiar pre-retirement list: read more, exercise more, travel, work around the house, and finally spend time on hobbies.
The problem was that vague hobbies produced vague days. “Exercise more” was easier to postpone than a Tuesday morning walking group, while “learn something” was easier to abandon than a class with a schedule.
He gradually turned wishes into commitments. Activities with a time, place, purpose, or other people attached to them were more likely to survive once the novelty of being off work faded.
Research on retirement and social roles suggests that meaningful activities can help provide purpose, identity, and structure when employment no longer fills those functions.
William therefore stopped asking only what he wanted to stop doing. He began asking what would give shape to an ordinary week after work disappeared completely.
13. His Final Day Felt Less Dramatic Than He Expected
After decades of work, William had imagined his last day would feel enormous. Instead, it felt surprisingly calm.
By then, most of the transition had already happened. Coworkers had taken over responsibilities, his household had adjusted to having him around more often, his finances had been tested at lower income levels, and his weekly routine no longer depended entirely on his employer.
That lack of drama turned out to be the payoff. Instead of retirement arriving as a sudden identity change, William’s final day was merely the last stage of a process that had been unfolding for three years.
Research does not show that phased retirement is universally superior.
Formal arrangements remain unavailable to many workers, and health problems, caregiving responsibilities, layoffs, employer policies, physical job demands, or financial pressure can make a gradual exit impossible.
U.S. research has also found that formal phased-retirement opportunities are relatively uncommon.
But for workers who have the option, gradually reducing hours can provide something a retirement calculator cannot: real-world information about how retirement actually feels.
What Someone Considering Phased Retirement Should Settle First
William’s experience does not mean everyone needs a three-year transition. Some people are financially and emotionally ready to leave immediately, while others may prefer part-time work for many years.
The useful idea is to test the parts of retirement that can be tested before making the employment decision irreversible.
| Question | What to Confirm Before Cutting Hours | Why It Matters |
|---|---|---|
| Can income drop safely? | Spending, savings rate, debt and cash reserve | Reduced hours mean reduced earnings |
| Will benefits change? | Health insurance, pension and workplace benefits | Eligibility may depend on hours |
| Will Social Security begin? | Claiming age and earnings-test effects | Work and claiming are separate decisions |
| What fills free time? | Activities, social contacts and weekly routine | Empty time does not organize itself |
| Can duties really shrink? | Written expectations and responsibility transfer | Part-time should not mean full-time workload |
| Is the household ready? | Spouse expectations and shared plans | Retirement changes life at home too |
A phased arrangement is therefore not simply “working less.” Done thoughtfully, it can become a controlled experiment in retirement living.
It can reveal whether the household budget feels realistic, whether friendships exist beyond work, whether healthcare has been coordinated correctly, and whether the retiree has enough structure to make freedom enjoyable rather than aimless.
Marco Kelley is a Retirement writer focused on helping older adults make confident, informed decisions about life after work. He covers retirement planning, Social Security, savings, taxes, healthcare costs, senior benefits, housing, and everyday financial choices. Marco brings a practical, straightforward approach to topics that can often feel complicated.
His goal is to give retirees and those nearing retirement clear guidance, useful ideas, and realistic strategies for building a more secure and comfortable future.