Returning to work at 70 can look simple on paper: earn a paycheck, add structure to the week, and leave retirement savings alone a little longer.
For Jimmy, the harder part was discovering that a job at 70 touches much more than income, from Medicare and taxes to energy, identity, and the rhythms of home.
The biggest surprises were not reasons to avoid working. They were reminders that working after 70 comes with a different set of tradeoffs, and understanding them early can make the decision much easier to manage.
Jimmy is an illustrative retiree used to explain common issues older Americans may encounter when returning to work. His situation is hypothetical, while the financial and benefit rules discussed below are based on current official guidance.
1. His Paycheck Could Make More of His Social Security Taxable
Jimmy initially looked at his new salary as completely separate from his retirement income. Federal tax rules do not necessarily treat the two that way, especially once Social Security is already arriving every month.
For federal income-tax purposes, the IRS uses a calculation that generally includes adjusted gross income, tax-exempt interest, and one-half of Social Security benefits.
The base amount is $25,000 for many single filers and $32,000 for married couples filing jointly, and at higher income levels as much as 85% of Social Security benefits can become taxable. That does not mean an 85% tax rate; it means up to 85% of the benefit may be included in taxable income.
Suppose a hypothetical single Jimmy received $30,000 a year from Social Security and then earned $35,000 at his new job. Before considering other adjustments, half of that Social Security benefit plus his wages would already total $50,000 for the basic Social Security taxation calculation.
That does not make returning to work a bad financial move. It simply means the number printed on the employment offer is not the same number that ultimately improves his household cash flow.
Here are several 2026 numbers someone in Jimmy’s position would want to know before accepting a job.
| Retirement Item | 2026 Figure or Rule | Why Jimmy Should Care |
|---|---|---|
| Social Security earnings test after full retirement age | No earnings limit reduces retirement benefits once full retirement age has been reached. | His paycheck does not cause benefits to be withheld under the earnings test. |
| Standard Medicare Part B premium | $202.90 per month in 2026. | Employment does not automatically eliminate existing Medicare costs. |
| First 2026 IRMAA threshold | Above $109,000 single or $218,000 married filing jointly, based generally on 2024 MAGI. | Higher earnings can influence Medicare premiums in later years. |
| 401(k)/403(b) employee deferral limit | $24,500, plus an $8,000 age-50-and-older catch-up if permitted. | A job can reopen a major tax-advantaged saving opportunity. |
| RMD age for Jimmy’s generation | Someone age 70 in 2026 generally falls in the cohort whose applicable RMD age is 73. | Returning to work does not make IRA RMD rules disappear. |
The important lesson for Jimmy was that gross salary was only the starting point. The more useful question was how much additional money remained after taxes, benefits, commuting costs, and changes elsewhere in his retirement plan.
2. Social Security Wasn’t Reduced, but Payroll Taxes Still Returned
Jimmy had heard people warn retirees that working could reduce their Social Security checks. At age 70, that particular warning was largely misplaced because the retirement earnings test stops applying once someone reaches full retirement age.
That did not mean the paycheck arrived untouched. Employees generally return to paying Social Security and Medicare payroll taxes on covered wages, just as they did before retirement.
There can also be a small upside. Social Security reviews beneficiaries’ earnings records, and if a new year of earnings is among a worker’s highest 35 years, SSA can recalculate the retirement benefit and pay an increase when appropriate.
For someone with 35 years of consistently strong earnings, another working year might make little or no difference. For someone whose record contains lower-earning years, however, returning to work could replace one of those years in the benefit calculation.
Jimmy therefore learned to separate two very different questions. Working at 70 would not trigger the retirement earnings test, but his new wages could still affect taxes and potentially his future Social Security calculation.
| What the New Wages Affect | At Age 70 | Practical Meaning |
|---|---|---|
| Social Security earnings test | Generally no reduction | Jimmy can earn wages without benefits being withheld because of the earnings test. |
| Social Security payroll tax | Still relevant on covered wages | Being 70 does not make wages automatically exempt from payroll taxes. |
| Social Security benefit calculation | Possibly | A strong earnings year can replace a lower year among the 35 years used by SSA. |
| Federal income taxes | Possibly significantly | Salary can increase taxable income and the taxable portion of Social Security. |
| Portfolio withdrawals | Potentially lower | Jimmy may be able to leave more money invested instead of withdrawing it for spending. |
The last row mattered more than Jimmy initially expected. A $30,000 or $40,000 paycheck could have value beyond the money deposited into checking if it also allowed him to reduce withdrawals from retirement savings.
3. Medicare Became More Complicated Instead of Disappearing
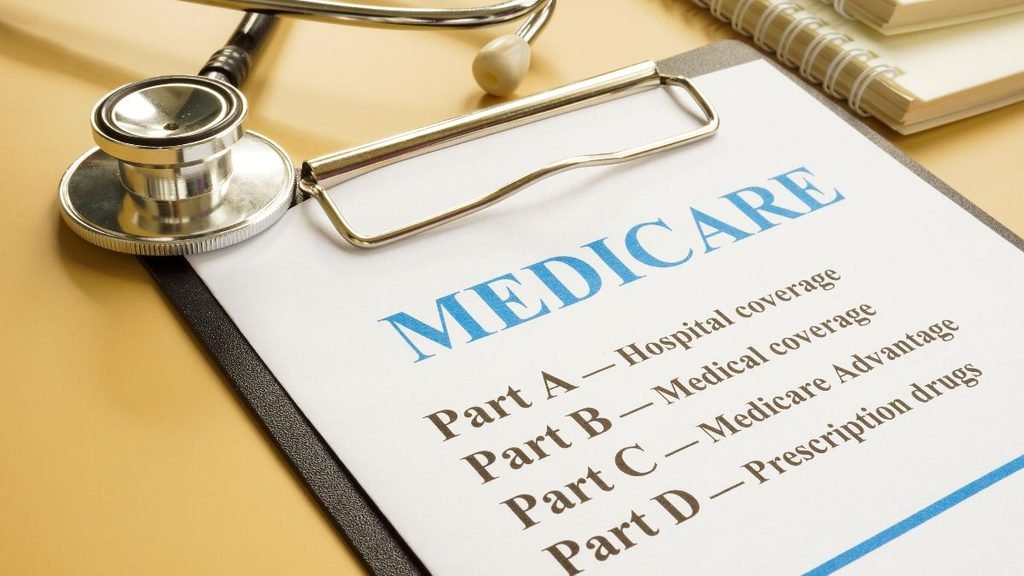
Jimmy assumed getting health insurance through an employer would make Medicare simpler. In reality, returning to a job at 70 can create another coordination decision instead.
Medicare advises people working past 65 to determine exactly how their employer’s plan coordinates with Medicare. Rules can differ based on the employer, type of coverage, and whether the coverage is considered active employer group health insurance.
Jimmy therefore could not safely assume that an employer health plan should replace Part B, that Medicare should automatically become secondary, or that dropping existing coverage would be harmless. His benefits department and Medicare coverage needed to be considered together.
There was also a longer-term issue: IRMAA. The standard Medicare Part B premium is $202.90 a month in 2026, but higher-income beneficiaries can pay substantially more.
Medicare generally determines IRMAA using modified adjusted gross income from two years earlier. For 2026 premiums, for example, Medicare generally looks at 2024 income, with the first IRMAA tier beginning above $109,000 for an individual or $218,000 for a married couple filing jointly.
That means Jimmy’s new 2026 wages would not normally raise his 2026 IRMAA simply because he started working that year. They could, however, matter when Medicare looks at that income for a later premium year.
4. An HSA Could Become an Expensive Little Mistake
One of the easiest retirement-work mistakes involves Health Savings Accounts. A worker who joins an HSA-eligible employer plan might naturally assume he can simply begin contributing again.
Medicare changes that calculation. IRS rules generally say an individual cannot make HSA contributions beginning with the first month in which the individual is enrolled in Medicare.
This issue can become particularly tricky for someone who delayed Medicare while working. Medicare warns that people with an HSA may need to stop contributions months before applying because Medicare Part A coverage can sometimes be retroactive.
Jimmy therefore needed to examine the health plan rather than automatically checking the HSA contribution box during enrollment.
| Benefits Question | What Jimmy Needs to Check | Why It Matters |
|---|---|---|
| Is he already enrolled in Medicare Part A? | Confirm his Medicare status before any HSA contribution. | Medicare enrollment generally makes him ineligible to contribute to an HSA. |
| Does the employer offer medical insurance? | Ask how the plan coordinates with Medicare. | Employer coverage does not automatically replace Medicare. |
| Does the job include prescription coverage? | Determine whether coverage is creditable and how it interacts with Part D. | Changing drug coverage without checking can create complications later. |
| Is the employer contributing to an HSA? | Tell benefits staff about Medicare enrollment. | An employer contribution can also create an excess HSA contribution problem. |
Jimmy did not need to become a Medicare expert just to take a job. He did, however, need a benefits conversation before the first contribution or coverage change was made.
5. A $25-an-Hour Job Wasn’t Really Worth $25 an Hour
Retirement changes the value of time. Before retirement, commuting and work clothes may simply be accepted as part of earning a living, but after someone has already regained control of the week, those costs become much more noticeable.
Jimmy had to think beyond salary. Transportation, parking, lunches, clothing, payroll taxes, additional income taxes, and occasional convenience spending could all reduce what the job added to his financial life.
The time cost mattered too. A five-hour shift could easily require another hour or two once getting ready, commuting, and recovering afterward were counted.
A better calculation was not simply annual salary. Jimmy needed to compare the extra after-tax household income with all the money and time required to earn it.
That distinction could make a flexible three-day schedule more attractive than a slightly better-paying five-day position. At 70, maximizing hourly pay was not necessarily the same as maximizing the value of working.
6. Returning to Work Reopened Retirement-Saving Opportunities
Jimmy initially thought retirement accounts belonged to his old working life. Starting another job meant some of those opportunities could become relevant again.
For 2026, the basic employee contribution limit for many 401(k), 403(b), and governmental 457 plans is $24,500. Workers age 50 and older can generally make an additional $8,000 catch-up contribution when the plan allows it.
An employer match could make the opportunity even more attractive. Jimmy therefore needed to read the new employer’s retirement-plan rules rather than assuming someone his age had no reason to enroll.
There was another clock approaching. Someone who is 70 in 2026 would generally fall within the group for whom RMDs begin at age 73 under current law.
Continuing to work can affect RMD timing for some employer plans. IRS guidance explains that a qualifying employer plan may allow a participant to postpone RMDs from that particular plan until retirement, depending on the circumstances and plan terms, but the same still-working exception generally does not postpone traditional IRA RMDs.
Jimmy therefore could not simply say, “I’m working again, so I don’t have to worry about RMDs.” The account type mattered as much as his employment status.
7. The Schedule Mattered More Than the Job Title
Jimmy remembered full-time work mainly through the lens of experience and competence. What he underestimated was how different the physical rhythm of a fixed schedule could feel after years of controlling his own mornings, meals, errands, appointments, and rest.
A job did not need to be physically demanding to become tiring. Commuting during rush hour, standing for long periods, concentrating for several hours, or waking to an alarm five mornings a week could change the way the rest of his day felt.
That did not mean a 70-year-old could not handle demanding work. It meant Jimmy benefited from judging a job by the entire weekly routine rather than simply asking whether he could perform the tasks.
Part-time work, later starting hours, remote days, shorter shifts, seasonal work, or consulting could sometimes preserve more of the freedom that made retirement attractive in the first place. The best arrangement depended on why Jimmy wanted to return.
8. He Had to Become the New Employee Again
Experience did not exempt Jimmy from onboarding. Software platforms, workplace messaging, cybersecurity procedures, scheduling systems, video meetings, and even expectations around communication may have changed considerably since he last held a similar role.
The uncomfortable part was not necessarily learning the technology. It was accepting that someone decades younger might be the person teaching him how the workplace now operated.
Jimmy’s previous experience still had value, but returning successfully required curiosity rather than constantly explaining how things had been done years earlier. Older expertise and newer workplace systems could coexist if neither was treated as automatically superior.
There was also the possibility of age bias. Federal law generally protects workers age 40 and older from age discrimination in hiring, firing, compensation, assignments, promotion, training, benefits, and other employment conditions for covered employers.
Not every awkward age-related comment is automatically unlawful discrimination. Still, Jimmy benefited from knowing that returning to work at 70 did not mean giving up ordinary workplace protections.
9. His Decision Affected More Than His Own Calendar
Retirement routines are rarely completely individual. A spouse or partner may have grown accustomed to shared breakfasts, weekday errands, spontaneous trips, helping grandchildren, appointments, or simply having another person around the house.
When Jimmy went back to work, those small arrangements could change. A job that looked like a personal decision on paper could quietly become a household scheduling decision.
That did not mean his family should decide whether he was allowed to work. It meant the conversation needed to include time, transportation, household duties, travel plans, caregiving responsibilities, and what each person expected retirement to look like.
This was especially important if the job was not financially necessary. When money was only one reason for returning, the household had more room to ask whether the schedule was improving retirement or simply filling it.
10. He Needed to Know How He Would Quit Before He Started
Jimmy’s biggest lesson was that returning to work should not become an accidental second career unless that was genuinely what he wanted. A job can slowly expand from two days a week to three, then additional projects, then weekend calls and responsibilities that begin following someone home.
Before his first day, Jimmy needed a definition of success. Perhaps he wanted to earn enough for travel, rebuild a cash reserve, delay portfolio withdrawals, spend more time around people, or simply have meaningful work twice a week.
He also needed an exit rule. If the job began interfering with health appointments, relationships, travel, sleep, or the activities he had retired to enjoy, he wanted permission to reconsider it without viewing that decision as failure.
A short checklist could have prevented many of the surprises.
| Priority | What Jimmy Should Decide | Practical Next Step |
|---|---|---|
| Money | How much additional after-tax income does he actually want? | Estimate taxes, commuting, meals, clothing, and benefit costs before accepting the offer. |
| Medicare | Will employer coverage change anything? | Speak with the benefits administrator and confirm the Medicare coordination rules. |
| Social Security | Could new earnings improve his record? | Review his SSA earnings history and watch for any future recalculation. |
| Retirement accounts | Is a 401(k), match, or catch-up contribution available? | Review the plan before automatically declining enrollment. |
| Time | How many hours still leave retirement enjoyable? | Set a weekly limit before work gradually expands. |
| Exit plan | What would make the job no longer worth keeping? | Choose two or three personal triggers that would cause him to reduce hours or leave. |
The goal was not to predict every possible problem. It was to make sure Jimmy remained the person controlling the job rather than allowing the job to quietly take control of retirement.
Marco Kelley is a Retirement writer focused on helping older adults make confident, informed decisions about life after work. He covers retirement planning, Social Security, savings, taxes, healthcare costs, senior benefits, housing, and everyday financial choices. Marco brings a practical, straightforward approach to topics that can often feel complicated.
His goal is to give retirees and those nearing retirement clear guidance, useful ideas, and realistic strategies for building a more secure and comfortable future.