Retirement can bring more free time without showing someone how to fill it. Picture Robert Miller, a fictional retiree, facing an empty Monday calendar and wondering what comes next.
Without work routines or daily contact with coworkers, the change may feel larger than expected. Unplanned costs, health coverage choices, and family demands can make the transition stressful.
The lessons in 18 Things I Wish I Knew Before I Retired offer practical ways to protect a budget, build new routines, and enjoy more satisfying days.
1. Retirement Days Feel Better With a Simple Weekly Schedule
After years of following a work schedule, having no fixed plans can feel strange. The first few weeks may be relaxing, but completely empty days can eventually become repetitive.
A simple weekly calendar gives retirement some structure without making it feel like another job. It helps retirees balance enjoyable activities, household responsibilities, appointments, and rest.
For example, Monday mornings might be reserved for grocery shopping, Wednesdays for meeting friends, and Fridays for a favorite hobby.
There is no need to fill every hour. Leaving open time for spontaneous plans is part of the benefit of retirement.
The goal is to have a few things to look forward to each week while still enjoying the freedom to change plans.
2. A Retirement Budget Needs Room for Unexpected Expenses
Many people prepare for retirement by estimating regular bills such as housing, groceries, insurance, and utilities. However, expenses that appear only a few times a year can be easier to overlook.
Car repairs, dental treatments, home maintenance, and family celebrations do not stop when someone retires. In some years, several of these costs may arrive close together.
A practical retirement budget should separate necessary monthly expenses from occasional spending.
| Expense Category | Commonly Overlooked Costs | Planning Approach |
|---|---|---|
| Housing | Repairs, insurance increases, property taxes | Set aside money monthly |
| Transportation | Tires, repairs, registration | Maintain a separate reserve |
| Health care | Dental care, glasses, prescriptions | Review coverage and likely costs |
| Family | Gifts, visits, celebrations | Set an annual spending limit |
| Leisure | Travel, classes, dining out | Use a flexible fun budget |
Reviewing bank and credit card statements from the previous year can reveal spending that was easy to forget.
Retirees who rent should also consider possible rent increases. The most useful budget is one based on real spending habits rather than an ideal month when nothing unexpected happens.
3. Claiming Social Security Early Can Reduce Monthly Benefits
Deciding when to claim Social Security is one of the most important financial choices many American retirees make.
Retirement benefits can begin as early as age 62. However, claiming before full retirement age generally results in a permanently reduced monthly benefit compared with waiting until that age.
For people born in 1960 or later, full retirement age is 67. Waiting beyond that age can increase the monthly retirement benefit until age 70.
| Claiming Age | Percentage of Full Retirement Benefit | Main Consideration |
|---|---|---|
| 62 | 70% | Payments start sooner, but at a reduced amount |
| 67 | 100% | Full retirement benefit for those born in 1960 or later |
| 70 | 124% | Higher monthly benefit, but payments begin later |
These percentages apply to a worker’s own retirement benefit for people born in 1960 or later. Actual payments depend on earnings history, claiming decisions, and other factors.
Waiting is not automatically the right choice for everyone. Health, savings, other income, and possible survivor benefits can all affect the decision.
Before applying, retirees can review personalized estimates through Social Security and compare how different claiming ages may affect their long-term finances.
4. Medicare Does Not Cover Every Health Care Expense
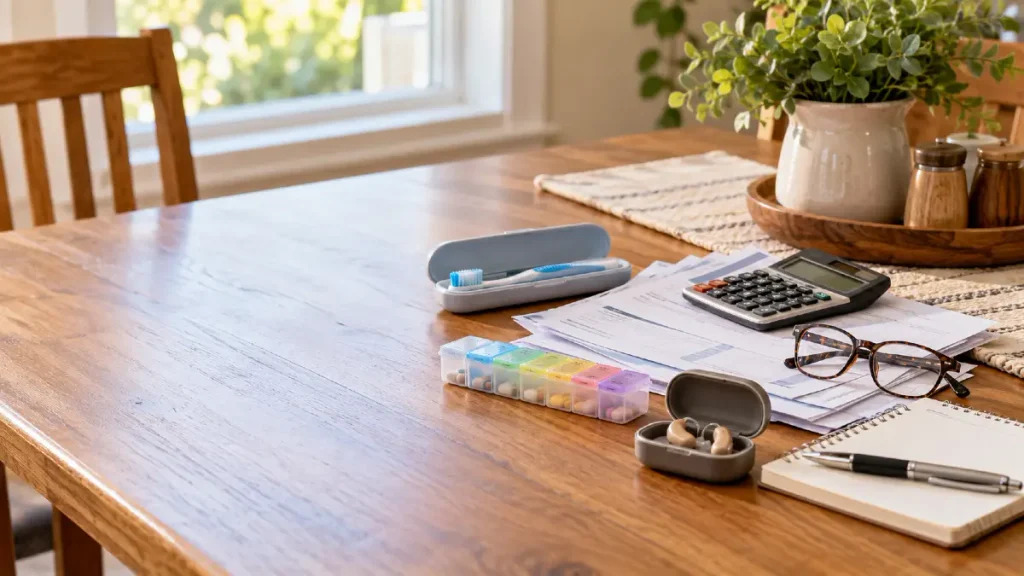
Turning 65 makes most Americans eligible for Medicare, but it does not mean every medical expense will be covered.
Original Medicare generally covers many hospital and medical services. It does not routinely cover most dental care, hearing aids, or eye exams for prescription glasses.
Medicare also does not pay for most long-term custodial care, such as ongoing help with bathing or dressing.
| Medicare Coverage | What Retirees Should Check |
|---|---|
| Part A | Hospital coverage, deductibles, and cost-sharing |
| Part B | Doctor visits, outpatient services, premiums, and deductibles |
| Part D | Prescription drug coverage and medication costs |
| Medigap | Help with certain Original Medicare out-of-pocket expenses |
| Medicare Advantage | Provider networks, drug coverage, extra benefits, and plan rules |
In 2026, the standard Medicare Part B premium is $202.90 per month, with higher premiums for some people based on income.
Most people first qualify for Medicare during a seven-month enrollment period surrounding their 65th birthday. Some people with qualifying coverage through current employment may be able to delay Part B enrollment without a penalty.
Retirees should review enrollment dates before leaving employer health insurance. Free counseling through a State Health Insurance Assistance Program can help explain coverage choices.
5. Paying Taxes Does Not Always End After Retirement
Leaving a full-time job does not necessarily mean the end of income taxes.
Withdrawals from traditional retirement accounts, pension payments, investment income, and part-time earnings may create taxable income. Depending on total income, some Social Security benefits may also be taxable.
Another important consideration is required minimum distributions, often called RMDs. These are withdrawals that generally must begin from certain retirement accounts at age 73 or 75, depending on birth year and account rules.
Tax rules can also provide benefits. For tax years 2025 through 2028, eligible Americans age 65 and older may qualify for an additional federal tax deduction, subject to income and other requirements.
A tax professional can help retirees plan withdrawals and avoid unpleasant surprises when filing their returns.
Tax rules differ outside the United States, so readers in Canada, the UK, and Australia should check the retirement-account and benefit rules that apply where they live.
6. Keeping an Emergency Fund Matters Even Without a Job
Retirement savings and emergency savings serve different purposes.
Money invested for long-term retirement income may not be convenient to access when the refrigerator breaks or a vehicle suddenly needs repairs.
Keeping an accessible cash reserve can reduce the need to sell investments or borrow money during an unexpected expense.
Common reasons for using an emergency fund include:
- Urgent home or vehicle repairs
- Unexpected medical or dental bills
- Emergency travel or temporary family needs
- A delay or change in expected income
The right amount depends on living costs, reliable income sources, insurance coverage, and personal circumstances.
Some retirees may need a larger reserve because they own an older home or have variable expenses. Others may have lower costs and steady pension income.
An emergency fund should be kept somewhere safe and reasonably easy to access, rather than invested in assets that can quickly lose value.
7. Staying Close to Former Coworkers Takes More Effort
Work friendships often grow naturally because people see each other every day. After retirement, those casual conversations and shared lunch breaks may disappear.
Even good friendships can become quieter when people no longer have the same schedule.
Retirees who value these relationships may need to make a little more effort to keep them active.
A monthly lunch, occasional phone call, or regular coffee meeting can help maintain the connection. Some former coworkers may still be busy with their jobs, so flexible plans often work better.
It is also normal for certain friendships to fade while others become stronger.
Keeping in touch with old colleagues can be enjoyable, but retired adults benefit from building relationships beyond their former workplace as well.
8. Joining a Local Club Makes New Friendships Easier
Making new friends after retirement often requires more planning than it did during working years.
Without daily contact with colleagues, people may have fewer chances to meet someone with similar interests.
A regular group activity can make conversations feel more natural. Book clubs, community classes, walking groups, and local recreation centers all provide opportunities to see familiar faces.
Someone who enjoys reading might begin with a monthly library book club. A person interested in gardening could visit a community garden or neighborhood gardening group.
The key is choosing an activity that meets regularly.
Friendships do not always develop after one visit. Attending several times allows people to recognize one another and build connections at a comfortable pace.
For retirees without easy transportation, online groups, telephone-based programs, and community transportation services may offer useful alternatives.
9. Volunteering Once a Week Can Bring a Sense of Purpose
Work often provides more than income. It may also offer a feeling of being useful, completing tasks, and contributing to something important.
After retirement, some people miss having responsibilities that matter to others.
Volunteering can provide that sense of purpose without requiring a full-time commitment. It also creates opportunities to meet people and use skills developed over many years.
| Volunteer Activity | Possible Time Commitment | Good Starting Point |
|---|---|---|
| Food pantry helper | A short weekly shift | Local food bank |
| Library volunteer | A few hours weekly | Public library |
| Reading tutor | One or two sessions weekly | School or literacy program |
| Animal shelter helper | Scheduled shifts | Local rescue organization |
| Museum volunteer | Regular or occasional shifts | Local museum |
These are examples rather than fixed schedules. Each organization has its own requirements, and some roles involve training or background checks.
A retiree could begin with one short shift each week and increase the commitment only if it remains enjoyable.
Volunteering should add satisfaction to retirement, not create another demanding schedule.
10. Walking, Strength Training, and Balance Exercises Deserve Time
Regular movement can become easier to neglect when the daily routine no longer includes commuting, walking around a workplace, or running errands during lunch breaks.
Physical activity helps support strength, mobility, independence, and general health.
The CDC recommends that adults age 65 and older aim for at least 150 minutes of moderate aerobic activity each week, or an equivalent amount of more vigorous activity.
The guidance also includes:
- Aerobic activity: Brisk walking, swimming, or other suitable movement
- Strength training: Muscle-strengthening activities at least two days weekly
- Balance exercises: Activities that challenge balance safely and regularly
A simple starting routine might include a short morning walk, light resistance exercises on selected days, and balance practice suited to the person’s abilities.
Exercise does not need to be complicated or expensive. Indoor walking, community fitness classes, and home exercise programs may also work.
People with medical concerns, recent injuries, or significant changes in fitness should discuss suitable activity with a health professional.
11. A Regular Sleep Schedule Still Matters Without an Alarm Clock
Retirement often removes the need to wake up early for work. That freedom is welcome, but an inconsistent sleep schedule can make ordinary days less enjoyable.
Staying awake late, sleeping far into the morning, and taking long afternoon naps may interfere with nighttime sleep for some people.
According to the National Institute on Aging, older adults generally need about seven to nine hours of sleep each night.
A steady bedtime and wake-up time can help support a regular sleep routine.
Morning daylight, comfortable bedroom conditions, and physical activity during the day may also be helpful.
Retirees can still enjoy occasional late evenings or relaxed mornings. The goal is consistency most of the time rather than a strict schedule.
Persistent sleep problems or excessive daytime sleepiness deserve medical attention instead of being dismissed as a normal part of getting older.
12. Trying a Hobby Before Buying Expensive Supplies Saves Money
Retirement can provide time for hobbies that were difficult to fit around a work schedule.
Painting, photography, gardening, music, and craft projects can all be enjoyable ways to spend an afternoon. However, it is easy to spend too much on equipment before knowing whether an activity will become a lasting interest.
Starting with borrowed supplies, beginner classes, or inexpensive materials makes exploring new hobbies more practical.
| Hobby | Low-Cost Starting Option | First Trial |
|---|---|---|
| Watercolor painting | Basic paint set and paper | One afternoon |
| Gardening | A few pots and seeds | One small planting project |
| Photography | Existing smartphone camera | A neighborhood photo walk |
| Learning music | Borrowed instrument or trial lesson | One beginner session |
| Birdwatching | Library bird guide or free identification resource | A short park visit |
Many libraries, community centers, and local clubs offer classes or shared equipment.
Some hobbies are naturally solitary, while others create opportunities for friendship.
A retiree who enjoys an activity after several attempts can gradually invest in better supplies. There is no need to build an expensive collection on the first day.
13. Retired Couples Need Both Shared Activities and Personal Space
Couples who spent years following different work schedules may suddenly find themselves home together for most of the day.
That change can be pleasant, but it may also require adjustments.
One partner may enjoy quiet mornings while the other prefers an early walk or a busy schedule. Different expectations do not mean the relationship is in trouble.
Maintaining separate hobbies and friendships can help both people enjoy their independence.
For example, one partner might attend a painting class while the other joins a walking group. They could then plan a shared dinner, weekend outing, or movie night.
Talking about household responsibilities is useful as well. Retirement does not automatically mean that either partner should take over every chore.
Couples who make room for personal interests and shared time may find the transition easier to manage.
14. Setting Boundaries With Family Protects Retirement Time
Family members sometimes assume that retirement means a person is available whenever help is needed.
A retired parent may be asked to provide regular childcare, handle errands, attend appointments with relatives, or take on household projects.
Helping family can be rewarding, but saying yes to every request can gradually consume the free time someone hoped to enjoy.
Clear expectations are useful from the beginning.
A retiree might agree to help with transportation on certain mornings while keeping other days available for personal activities.
Family members can also benefit from knowing which responsibilities are realistic and which require advance notice.
These conversations should be respectful and flexible, especially when someone has genuine caregiving needs.
Retirement can include generosity and family support without requiring a person to remain available every hour of the week.
15. Part-Time Work Can Be Enjoyable After Full-Time Retirement
Some retirees discover that they miss certain parts of employment.
They may enjoy working with people, solving problems, teaching skills, or earning additional spending money.
A part-time job can provide those benefits without recreating the demands of a full-time career.
Possible options include tutoring, consulting, seasonal retail work, administrative support, or helping a local nonprofit.
However, work should fit the retiree’s energy, transportation, income needs, and preferred schedule.
For Americans receiving Social Security before full retirement age, employment earnings can affect benefit payments.
In 2026, people who remain below full retirement age for the entire year generally have an annual earnings limit of $24,480 before Social Security begins withholding benefits under the earnings test. Different rules apply during the year full retirement age is reached.
Withheld benefits are accounted for when Social Security recalculates benefits at full retirement age.
Returning to paid work does not mean retirement has failed. It can simply be another way to spend time, provided the commitment remains worthwhile.
16. Short Trips Can Be More Enjoyable Than Constant Expensive Travel
Travel is one of the most common retirement goals, but frequent vacations are not always practical.
Flights, hotels, meals, transportation, and travel insurance can become expensive. Long itineraries may also leave less time for rest than expected.
Instead of planning several major vacations immediately, retirees can begin with nearby destinations.
A day trip to a botanical garden, historic town, museum, or scenic park may provide a pleasant change without a large budget.
When planning longer trips, it helps to consider:
- Total expenses: Include transportation, meals, lodging, and unexpected costs.
- Energy and comfort: Allow enough time for breaks and avoid overcrowded itineraries.
- Medical coverage: Check whether existing insurance covers care away from home or overseas.
Original Medicare generally provides little coverage for medical care outside the United States, with limited exceptions. International travelers may need separate coverage.
Weather, accessibility, and available transportation also deserve attention.
Some retirees may prefer two comfortable short vacations each year over a packed schedule of expensive trips.
17. A Home and Transportation Plan Should Fit Future Daily Needs
A house that worked well during full-time employment may not remain the best fit for every stage of retirement.
Some people enjoy maintaining a large property, while others become tired of managing repairs, cleaning unused rooms, or driving long distances for everyday needs.
Retirement offers an opportunity to think about convenience before a major change becomes necessary.
| Area to Review | Practical Question | Possible Adjustment |
|---|---|---|
| Home maintenance | Is the upkeep affordable and manageable? | Hire occasional help or simplify tasks |
| Stairs and entrances | Is movement through the home comfortable? | Improve lighting, rails, or access |
| Transportation | Are essential places easy to reach? | Explore public or community transport |
| Shopping | Are groceries and services convenient? | Try delivery or local shopping options |
| Social access | Are friends and activities reasonably close? | Look for nearby programs or groups |
These questions do not mean every retiree needs a smaller home or a move.
Someone may be perfectly comfortable in a longtime home with no changes at all. Another person may prefer a walkable apartment near shops and friends.
The important lesson is to review housing and transportation before maintenance costs or access problems become overwhelming.
18. Organizing Important Documents Can Prevent Future Problems
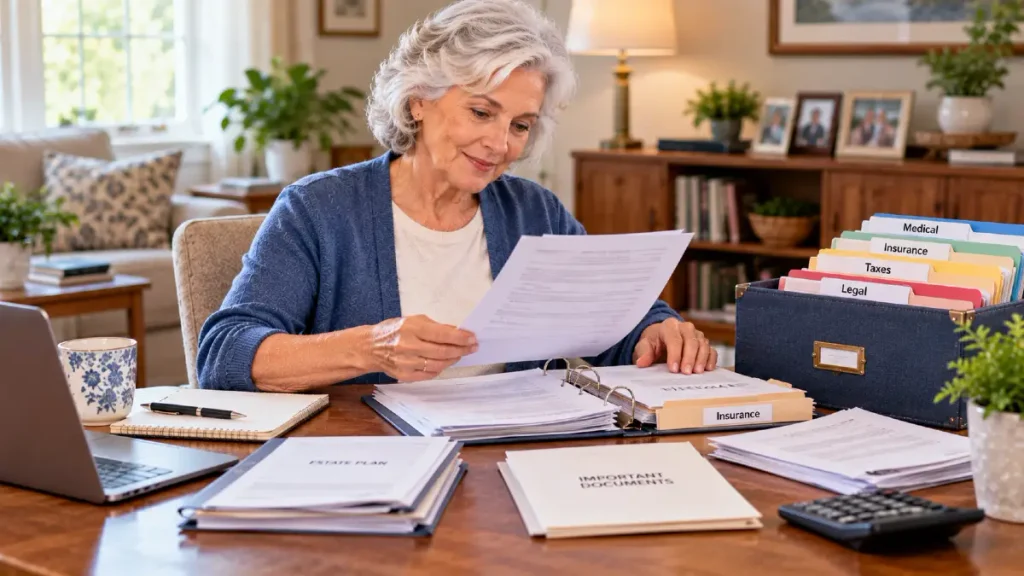
Retirement planning often focuses on income and leisure, but organizing personal and financial documents is equally important.
When information is scattered across drawers, accounts, and filing cabinets, even a simple emergency can become difficult for loved ones or trusted helpers to manage.
A basic document folder can make important details easier to locate.
Useful items to review include:
- Legal documents: Wills, advance health care directives, and powers of attorney
- Financial records: Bank accounts, pensions, retirement plans, and insurance policies
- Beneficiary information: Current names listed on retirement and insurance accounts
- Trusted contacts: People who can help during a medical or financial emergency
Estate planning rules vary by state and country, so legal documents should be reviewed with a qualified professional when needed.
Retirees should also protect sensitive information. Passwords and personal records should be stored securely rather than left in an openly accessible folder.
The Consumer Financial Protection Bureau also encourages planning ahead for financial emergencies and choosing trusted contacts when appropriate.
Organizing these details while life is calm gives retirees more control over how important decisions are handled.
A Small Change Can Make Retirement More Enjoyable
Retirement does not need to be perfectly planned from the beginning. Spending habits, interests, relationships, and daily routines may change as people discover what suits them.
A useful first step is to write down three things that would make an ordinary retirement week feel satisfying.
Those three ideas can become the starting point for a realistic weekly routine, leaving plenty of room for new interests and changing plans.
Frequently Asked Questions
What Do Most People Wish They Had Known Before Retirement?
Many retirees wish they had prepared for the lifestyle changes as carefully as the financial ones. Creating a routine, maintaining friendships, understanding health coverage, and planning for unexpected expenses can make the transition smoother. The most important lesson often depends on the person’s health, finances, relationships, and interests.
How Long Does It Take to Adjust to Retirement?
There is no fixed adjustment period. Some people enjoy their new schedule immediately, while others need time to establish hobbies, friendships, and daily routines. Trying different activities gradually may help, and persistent sadness or anxiety is worth discussing with a health professional.
How Can Someone Enjoy Retirement Without Spending Much Money?
Enjoyable retirement activities do not always require expensive equipment or travel. Public libraries, local parks, community programs, volunteering, walking groups, and home-based hobbies may offer free or inexpensive options. Checking local programs can reveal activities that fit different budgets and abilities.
What Should Someone Do During the First Month of Retirement?
The first month can be used to rest, review monthly expenses, organize appointments, and try a simple weekly schedule. It is also a good time to reconnect with friends and explore one new interest. Major purchases or permanent lifestyle changes do not have to happen immediately unless a financial, medical, or practical need makes them necessary.