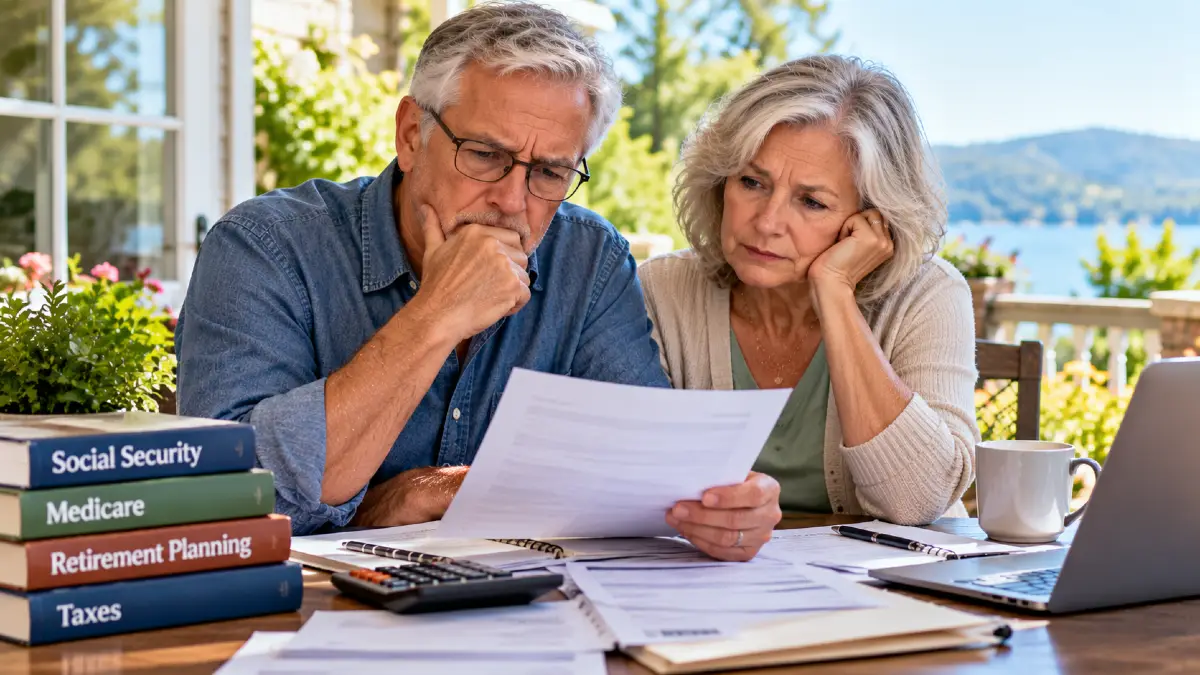
Leaving work changes more than your schedule. The regular paycheck stops, weekdays lose their shape, and decisions that once felt easy may suddenly seem harder. Even retirees who planned carefully can feel caught off guard.
A few early missteps can make that adjustment harder. Missed insurance deadlines, rushed spending, and long stretches without social contact may bring stress when you expected more freedom.
The following 15 retirement mistakes that ruin the first year are worth watching for, but many are avoidable. These practical tips can help protect your money, health, relationships, and time.
1. Retiring Without a Real Monthly Budget
Many people spend years saving for retirement but much less time planning how they will spend their money once they stop working.
A retirement budget needs to reflect your new income and everyday expenses. Social Security, pensions, savings withdrawals, and part-time earnings may arrive at different times.
Start by writing down how much money you expect to receive each month. Then compare that amount with your regular bills, groceries, transportation, insurance, and personal spending.
Don’t forget expenses that arrive only a few times a year. Property taxes, insurance renewals, holiday gifts, and vehicle repairs can create problems when they are missing from your plan.
| Budget Category | What to Check |
|---|---|
| Monthly income | Expected payments and deposit dates |
| Essential expenses | Housing, groceries, utilities, and insurance |
| Flexible spending | Dining, entertainment, shopping, and hobbies |
| Occasional bills | Property taxes, repairs, and annual renewals |
| Emergency savings | Money available for unexpected costs |
Your first budget will probably need adjustments. Reviewing what you actually spend each month can help you make changes before small problems become larger ones.
2. Assuming Everyday Expenses Will Automatically Drop
Some retirees expect their monthly expenses to fall sharply once they stop commuting and buying work clothes.
Certain costs may disappear, but other expenses can grow. Spending more time at home may affect utility bills, groceries, entertainment, and household supplies.
Free time can also create new spending habits. A casual lunch out, an afternoon shopping trip, or another streaming subscription might seem harmless on its own.
These purchases can add up when they become part of your weekly routine.
Before retirement, compare your current spending with the lifestyle you actually want. Include realistic costs for hobbies, travel, family visits, and healthcare.
A useful approach is to track expenses closely during your first three months. This helps separate one-time retirement celebrations from purchases that may continue throughout the year.
3. Claiming Social Security Without Comparing Different Ages
Starting Social Security immediately after leaving work may feel like the natural next step. However, your retirement date and your Social Security claiming date do not have to be the same.
In the United States, eligible workers can generally begin receiving Social Security retirement benefits at age 62. Claiming before full retirement age reduces the monthly benefit compared with waiting.
For people born in 1960 or later, full retirement age is 67. Delaying benefits beyond full retirement age can increase the monthly payment until age 70.
| Claiming Age | What It Means | Important Consideration |
|---|---|---|
| Age 62 | Earliest retirement claiming age for most workers | Lower monthly benefit |
| Full retirement age | Unreduced retirement benefit | Age depends on birth year |
| Age 70 | Maximum delayed retirement credits | Requires waiting longer for payments |
Claiming early is not automatically a mistake. Health, other income, family circumstances, and immediate financial needs can make earlier benefits reasonable.
Before applying, compare your personalized estimates through your Social Security account. Married retirees should also consider how the decision may affect survivor benefits.
If you plan to work while receiving benefits before full retirement age, check the Social Security earnings rules as well.
4. Missing an Important Medicare Enrollment Deadline
Health insurance can become confusing when retirement happens near age 65.
Many Americans become eligible for Medicare at 65, but leaving a job does not automatically mean every part of Medicare coverage is active.
For most people, the initial Medicare enrollment period lasts seven months. It begins three months before the month they turn 65 and ends three months afterward.
Some people are enrolled automatically. Others must take action.
People who continue working beyond 65 may qualify for a special enrollment period if they have eligible employer group health coverage. For Medicare Part B, that period generally lasts eight months after employment or qualifying coverage ends, whichever occurs first.
Before leaving work:
- Check your enrollment status. Confirm whether you are enrolled automatically or need to apply.
- Speak with your benefits office. Find out how your employer coverage coordinates with Medicare.
- Review prescription coverage. Determine whether your current drug plan meets Medicare’s creditable coverage rules.
- Confirm important dates. COBRA and retiree health coverage generally do not extend the Part B special enrollment period.
Missing certain enrollment deadlines can lead to coverage gaps or lasting premium penalties.
Medicare rules are specific to the United States. Retirees in other countries should review the enrollment and coverage rules for their own healthcare systems.
5. Forgetting About Medical and Dental Expenses
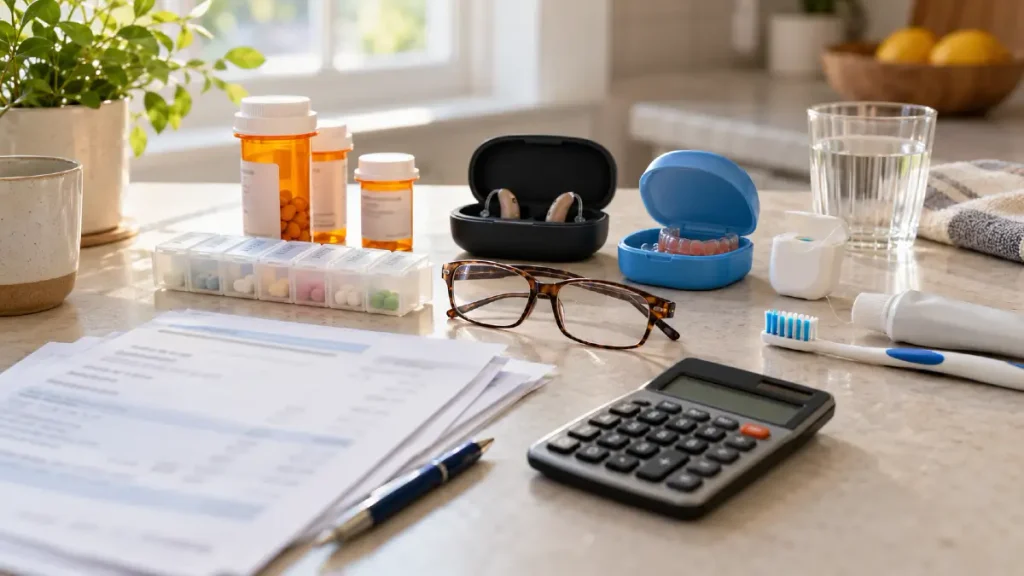
One of the biggest retirement budgeting mistakes is assuming Medicare will pay for every healthcare expense.
Original Medicare covers many medically necessary services, but it does not cover everything. Premiums, deductibles, copayments, and coinsurance may still apply.
Routine dental care, hearing aids, and certain vision services are generally outside Original Medicare coverage. Nonmedical long-term care is another major expense that Medicare usually does not pay for.
| Healthcare Expense | Coverage Issue | What to Review |
|---|---|---|
| Routine dental care | Usually not covered by Original Medicare | Dental benefits or separate coverage |
| Eyeglasses and routine eye exams | Often not covered | Vision coverage and personal budget |
| Hearing aids | Generally not covered by Original Medicare | Hearing benefits or out-of-pocket costs |
| Prescription drugs | Coverage depends on the drug plan | Drug lists, pharmacies, and plan costs |
| Long-term personal care | Generally not covered by Medicare | Savings and long-term care options |
Some Medicare Advantage plans offer additional dental, vision, or hearing benefits. Coverage, provider networks, and costs vary by plan.
Medigap policies can help with certain out-of-pocket costs under Original Medicare, but they are not a general replacement for dental or long-term care coverage.
Review your medical needs, current prescriptions, and insurance choices before your employer coverage ends.
Retirees who leave work before age 65 should also arrange suitable insurance. Losing job-based coverage may qualify them for a special enrollment period through the Health Insurance Marketplace.
6. Taking Too Much Money From Retirement Savings Too Soon
After years of working and saving, it can feel rewarding to finally use the money you have built up.
A new car, home renovation, expensive vacation, or generous family gift may seem like a reasonable way to celebrate.
The concern is how large early withdrawals affect your savings over the following years.
Money withdrawn today is no longer available for future expenses or possible investment growth. Large withdrawals during a market decline may be particularly difficult because they can force you to sell investments when their values are down.
Consider setting a planned withdrawal amount based on your expected expenses, investment mix, income sources, and retirement goals.
Review that amount regularly rather than assuming the same withdrawal strategy will work forever.
There is no single withdrawal percentage that guarantees your money will last. A qualified financial planner can help assess a strategy that fits your circumstances.
7. Forgetting That Taxes Continue After Retirement
Stopping work does not necessarily mean your federal income tax bill disappears.
Many retirees receive money from several sources, and those payments may receive different tax treatment.
Traditional IRA and 401(k) withdrawals are generally taxable, although exceptions can apply. Pension payments may also be taxable, while Social Security benefits can be partly taxable depending on your overall income.
| Retirement Income | General U.S. Tax Treatment |
|---|---|
| Social Security | May be partly taxable depending on other income |
| Traditional IRA withdrawals | Generally taxable, subject to any after-tax basis |
| Traditional 401(k) withdrawals | Generally taxable |
| Qualified Roth withdrawals | Generally tax-free |
| Pension payments | May be fully or partly taxable |
Taking a large distribution from a retirement account could increase taxable income for the year.
Retirees should also check whether they need estimated tax payments or withholding from benefits and retirement accounts.
Required minimum distribution rules become important later for many retirement accounts. The starting age and requirements depend on the account type and birth year.
During your first year, consider meeting with a tax professional to review your withdrawal plans. This is especially helpful if you retired partway through the year or received a final paycheck, bonus, or vacation payout.
8. Spending Emergency Savings on Retirement Celebrations
The first few months of retirement can bring a strong desire to celebrate.
A long-awaited vacation or home improvement project may be part of a well-earned retirement plan. The problem begins when major purchases use money that was intended for emergencies.
Cars still need repairs. Appliances can fail, insurance costs can change, and unexpected travel may become necessary.
An emergency fund provides a financial cushion without requiring an immediate withdrawal from long-term investments.
Before making a major purchase, consider these steps:
- Keep emergency savings separate from money reserved for travel and hobbies.
- Plan ahead for predictable repairs and annual bills.
- Review the effect of a large purchase on future monthly spending.
- Avoid taking on new debt without understanding how payments fit your retirement income.
The right amount of emergency savings depends on your housing situation, income stability, insurance, and access to other funds.
A renter with predictable expenses may have different needs from a homeowner responsible for major repairs.
Enjoying retirement does not require avoiding every large purchase. It means making those purchases without leaving yourself financially exposed.
9. Selling Your Home or Moving Too Quickly
Relocating after retirement can be appealing, especially if you have dreamed about warmer weather, a smaller home, or living closer to family.
However, the first year may not be the best time to make a permanent decision based only on how retirement feels during the first few months.
A location that seems perfect during a vacation might feel different during the hottest summer weeks or the coldest part of winter.
Housing costs also involve more than the purchase price or monthly rent. Property taxes, insurance, maintenance, moving expenses, and transportation can make a seemingly affordable location more expensive.
Before relocating, consider how easily you can access healthcare, grocery stores, friends, and activities.
For people who no longer drive or prefer not to, public transportation and walkable neighborhoods may be particularly important.
If your circumstances allow, try an extended visit or short-term rental before making a final commitment.
There is no need to delay a move that is necessary for safety, affordability, or care. The important point is to make housing decisions based on practical needs rather than temporary frustration or excitement.
10. Waking Up Every Day Without a Weekly Schedule
One surprising retirement mistake is assuming that having nothing planned will always feel relaxing.
At first, sleeping later and enjoying slow mornings may be exactly what you need.
After a while, however, days without structure can begin to feel repetitive. Household tasks get postponed, appointments are forgotten, and enjoyable activities never quite happen.
A simple weekly routine provides direction without recreating the pressure of a full-time job.
You do not need to schedule every hour. A few regular activities can make your week feel more balanced.
| Weekly Routine | Simple Example | Main Purpose |
|---|---|---|
| Daily morning activity | Walk, stretch, or enjoy breakfast outside | Start the day with a familiar habit |
| Twice a week | Attend a class or work on a hobby | Maintain personal interests |
| Once a week | Meet a friend or join a community activity | Stay socially connected |
| Weekly home task | Shop, clean, or manage paperwork | Keep responsibilities manageable |
| Flexible free time | Read, rest, explore, or visit family | Leave room for enjoyment |
Choose activities that match your energy, interests, transportation options, and budget.
A useful retirement schedule should support your freedom rather than take it away.
11. Losing Contact With Friends After Leaving Work
Work often creates regular social contact without much planning.
You may talk with coworkers over lunch, share stories during breaks, or see familiar faces throughout the day.
After retirement, those casual conversations can disappear almost overnight.
Some work friendships continue naturally. Others fade because everyone returns to different schedules and responsibilities.
The National Institute on Aging explains that loneliness and social isolation are associated with several health concerns, including depression and poorer cognitive health.
Living alone does not automatically mean someone is lonely. Likewise, living with a partner does not guarantee enough social connection.
Maintaining friendships takes some effort, but it does not have to be complicated.
Invite a former coworker for coffee, arrange a regular phone call, or join a local class where people share your interests.
Libraries, community centers, volunteer groups, and neighborhood organizations can provide opportunities to meet others.
For retirees with transportation or mobility concerns, telephone calls, video chats, and accessible community programs may be useful alternatives.
The goal is not to fill your calendar with people. It is to maintain a few relationships that genuinely matter.
12. Spending Most of the Day Sitting Down
Retirement can quietly change how much you move.
Even jobs that involve sitting may include walking through an office, using stairs, visiting coworkers, or traveling between locations.
Once those daily movements disappear, it becomes easier to spend long periods watching television, reading, or sitting at a computer.
Regular physical activity supports strength, balance, heart health, and everyday independence.
The CDC recommends that adults age 65 and older aim for at least 150 minutes of moderate-intensity aerobic activity each week, along with muscle-strengthening activities on at least two days and activities that improve balance.
That does not mean everyone needs to start with long walks or demanding workouts.
Gardening, water exercise, gentle walking, dancing, and suitable strength exercises may all have a place in an active routine.
Physical abilities differ, and activities can often be adapted. Someone with joint problems, a heart condition, or balance concerns may benefit from discussing a suitable plan with a healthcare professional.
Start at a level that feels manageable and increase gradually when appropriate.
A short movement break between periods of sitting can also help you make physical activity part of your normal day.
13. Expecting Your Spouse to Spend Every Hour Together
Retirement can change a couple’s daily routine more than either person expects.
One partner may look forward to shared breakfasts, outings, and projects. The other may prefer quiet time, familiar routines, or separate hobbies.
Neither preference is necessarily wrong.
Problems can develop when one person expects retirement to mean doing everything together while the other needs more personal space.
These differences may become especially noticeable when one spouse retires before the other.
Instead of assuming you have the same expectations, talk about how you each want to spend your days.
Plan some activities together, such as weekly walks, meals out, or short trips. Leave room for individual interests, friendships, and relaxation.
Household responsibilities may need another discussion, too. A newly retired partner should not automatically assume every household task, but the couple may benefit from reviewing what feels fair.
A healthy retirement relationship allows both shared experiences and personal independence.
For people who are single or live alone, maintaining a mix of solo interests and chosen social activities can provide similar balance.
14. Saying Yes to Every Family Request
Retirement often brings more flexibility, which family members may appreciate.
Adult children might ask for help with errands, grandchildren, home repairs, appointments, or caregiving responsibilities.
Helping loved ones can be deeply rewarding. However, being retired does not mean every day is automatically available.
Some retirees gradually discover that their schedules have become filled with other people’s needs.
There may be little time left for their own hobbies, rest, travel, or friendships.
Setting boundaries early can prevent resentment and confusion.
Consider a few practical approaches:
- Offer specific times. Explain which days or hours you are usually available to help.
- Discuss regular commitments. Agree on expectations before taking on ongoing childcare or caregiving duties.
- Protect personal plans. Treat your own appointments and activities as meaningful commitments.
- Share responsibilities. When possible, involve other family members or community support services.
Occasional favors are different from becoming someone’s full-time caregiver.
If caregiving becomes a major responsibility, consider its emotional, physical, and financial demands before agreeing to an ongoing arrangement.
Your retirement time has value, even when you are not earning a paycheck.
15. Trusting Financial Offers That Promise Easy Retirement Income
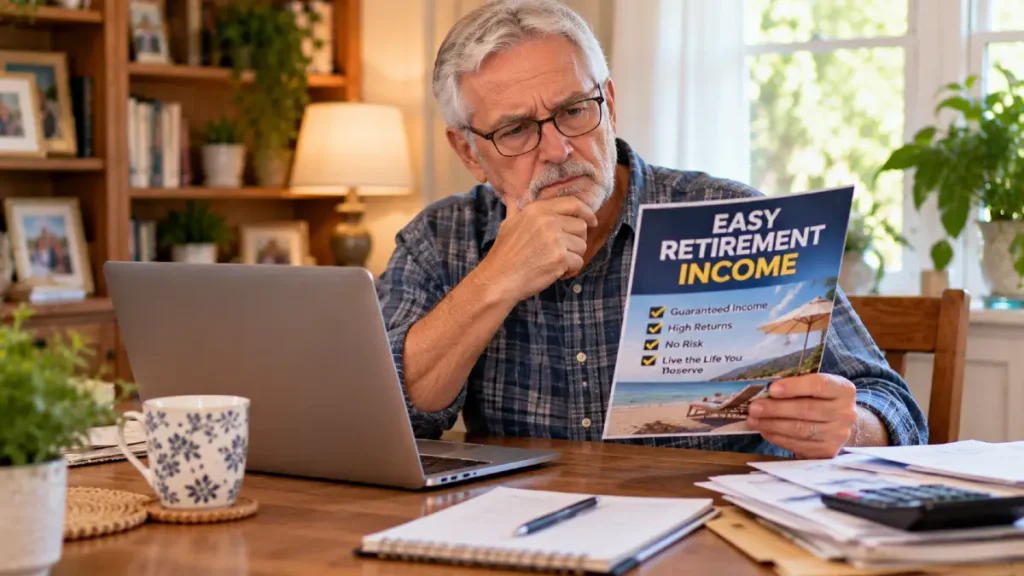
Retirees may receive calls, messages, or advertisements promising special investment opportunities.
Some offers claim to provide guaranteed high returns, unusually safe investments, or quick ways to increase retirement income.
These claims deserve careful attention.
The Federal Trade Commission warns that guaranteed profits, pressure to act immediately, and promises of little or no investment risk are common signs of investment scams.
Scammers may pretend to represent government agencies, financial firms, or trusted organizations. A convincing voice or professional-looking document does not prove that an offer is legitimate.
| Warning Sign | Safer Response |
|---|---|
| Guaranteed high investment returns | Question the claim and investigate independently |
| Pressure to send money immediately | Stop the conversation and take time to verify |
| Unexpected request for account information | Contact the organization through a trusted number |
| Secret or exclusive investment opportunity | Check registration, risks, and written details |
| Requests to transfer funds to a new account | Confirm instructions directly with your financial institution |
Do not share account passwords, verification codes, or sensitive financial information with someone who contacts you unexpectedly.
If an investment adviser recommends a new product, ask about fees, risks, access to your money, and whether the recommendation suits your needs.
It is reasonable to get a second opinion before moving retirement savings.
Protecting your finances requires the same careful judgment during retirement that helped you build those savings in the first place.
Make Your First Year of Retirement Work for You
Your first year of retirement does not need to be perfectly planned. Some routines will change, new interests may develop, and certain expectations will probably need adjusting.
The most useful approach is to notice small problems before they become difficult to manage.
This week, write down the one retirement mistake from this list that concerns you most and one practical action you can take to avoid it.
A thoughtful first step can make the months ahead feel more manageable.
Frequently Asked Questions
Can You Retire at 62 Without Claiming Social Security?
Yes. Retiring from work and starting Social Security retirement benefits are two separate decisions. Eligible workers can generally claim from age 62 through age 70, with different monthly benefit amounts. If you retire before 65, you will also need to consider health insurance until Medicare eligibility, unless you qualify earlier for another reason.
What Is the Hardest Adjustment During the First Year of Retirement?
The hardest adjustment varies from person to person. Some retirees find it difficult to manage money without a regular paycheck, while others miss workplace friendships, daily structure, or a sense of purpose. Building a flexible routine and reviewing finances can help with several of these changes.
How Often Should You Review Your Retirement Budget During the First Year?
A monthly review is useful during the early months because your actual spending may differ from your expectations. Once your income and expenses become more predictable, you may find that less frequent reviews work well. Revisit your budget whenever major expenses, income, health needs, or housing costs change.
What Should You Do If Retirement Feels Boring or Lonely?
Start by adding one regular activity that gives you something to look forward to, such as a class, walking group, volunteer commitment, or weekly visit with a friend. Allow time to adjust without expecting every day to be busy. If loneliness or persistent low mood begins affecting your daily life, consider talking with a healthcare professional.