

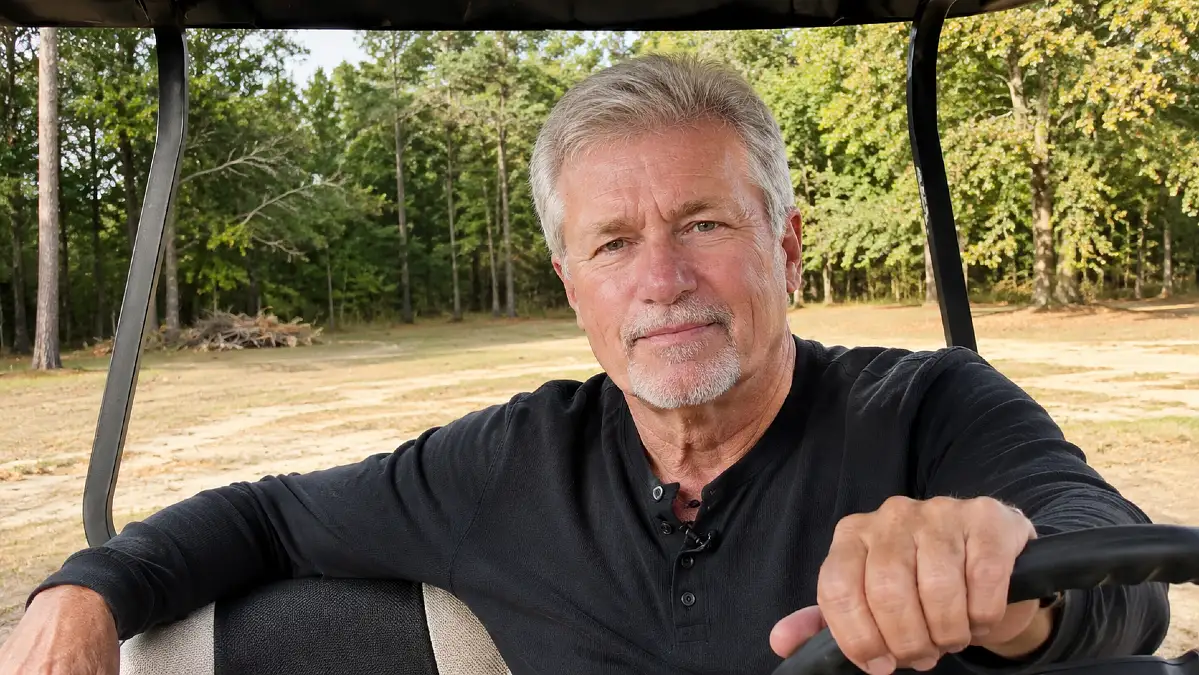
Ronnie Christian spent much of his adult life believing the same rule many Americans hear. Work hard, stay busy, keep pushing, and do not stop too soon.
When he finally quit the rat race at 61, the biggest surprise was not boredom or fear. It was how much relief he felt once work stopped controlling his time.
At 61, however, freedom comes with real financial complications. Social Security retirement benefits generally cannot begin until 62, while Medicare usually does not begin until 65.
Note: This article provides general educational information and is not individualized financial, tax, investment, legal, or Social Security advice. Rules and personal circumstances vary, so verify current official guidance before making major retirement decisions.
Ronnie Christian Didn’t Miss What He Thought He Would Miss
Before leaving work, Ronnie heard the usual warnings. He might miss the routine, coworkers, daily structure, status, and sense of purpose.
Instead, he says he missed very little. What stood out most was the disappearance of pressure.
Sunday night anxiety was gone. So were after hours emails, morning commutes, office politics, and the feeling that every weekday belonged to someone else.
That does not happen for every retiree. Some people deeply enjoy their careers and feel genuine loss when their work identity disappears.
Retirement research supports both possibilities. Some studies have found improvements in life satisfaction after retirement, especially when leaving demanding work conditions.
Ronnie’s experience fits one side of that picture. His retirement did not feel like losing purpose as much as losing pressure.
| 2026 Retirement Item | Current Rule or Figure | Why It Matters at 61 |
|---|---|---|
| Earliest Social Security retirement benefit | Age 62 | A 61 year old usually needs another income source |
| Full retirement age | 67 for people born in 1960 or later | Early claiming permanently reduces benefits |
| Medicare eligibility | Generally age 65 | Healthcare may need funding for about four years |
| 2026 401(k) contribution limit | $24,500 | Leaving work ends future salary deferrals |
| Ages 60 to 63 catch up | $11,250 in 2026 | These workers have an unusually large saving opportunity |
| 2026 Social Security COLA | 2.8% | Current benefits rose with inflation adjustments |
This is one of the biggest distinctions in Ronnie’s story. Being emotionally ready to leave work and financially ready to leave work are not the same thing.
A person can feel completely finished with a career while still needing a careful bridge between employment and retirement benefits.
Age 61 Is an Awkward Retirement Age Financially
Age 61 feels close to traditional retirement. Financially, however, it sits just before several important milestones.
A 61 year old generally cannot yet claim Social Security retirement benefits. Medicare is also usually about four years away.
For people born in 1960 or later, Social Security full retirement age is 67. Claiming at 62 can reduce the monthly retirement benefit by as much as 30% compared with waiting until full retirement age.
Waiting beyond full retirement age can increase the monthly worker benefit. For someone with an FRA of 67, delayed retirement credits can raise the benefit until age 70.
That does not mean everyone should wait until 70. Health, cash needs, longevity expectations, spouse benefits, and household finances can all change the decision.
| Age | Main Opportunity | Main Advantage | Main Tradeoff |
|---|---|---|---|
| 61 | Leave work using other resources | Immediate freedom | No regular Social Security retirement benefit yet |
| 62 | Social Security can begin | Income begins sooner | Benefit may be permanently reduced |
| 65 | Medicare generally starts | Major healthcare milestone | Still before FRA for many retirees |
| 67 | FRA for people born 1960 or later | Full calculated retirement benefit | Requires waiting longer |
| 70 | Maximum delayed credits reached | Larger monthly worker benefit | Requires more years of bridge funding |
Ronnie’s choice therefore was not just about leaving a job. It meant entering several years when personal savings and other resources had to carry more of the load.
That is why retiring at 61 can feel emotionally simple while remaining financially complex.
Time Started Feeling Completely Different
One of Ronnie’s strongest observations was that work controlled more of his time than he had realized. It shaped mornings, evenings, sleep, meals, traffic, weekends, and even thoughts about Monday.
After leaving, his days stopped feeling like blocks of time that had to be managed around work. Mornings became slower and less rushed.
Ronnie and his wife could sit with coffee without watching the clock. They could take turns making breakfast and let the morning unfold naturally.
On one morning, Ronnie prepared grits, eggs, sausage, and French toast. The meal itself was simple, but having the time to make it felt completely different.
That is one of the less discussed benefits of retirement. The value of time can become more visible once another person or company no longer controls most weekdays.
A retiree may lose wages but gain hundreds of hours each year. Those hours previously went to commuting, preparation, overtime, recovery, and worrying about work.
Ronnie Was More Burned Out Than He Realized
Ronnie says he did not fully understand how tired he had become until he stopped feeling tired all the time.
During his working years, some mornings began with exhaustion. Sleep did not always leave him feeling restored.
Over time, that level of fatigue began to feel normal. He simply learned to push through it and return to work again.
That does not mean retirement automatically cures fatigue. Persistent exhaustion can have many causes and may need medical attention.
Still, some retirement research has found improvements in sleep and life satisfaction after people leave demanding jobs. That gives useful context to Ronnie’s experience without turning it into a medical claim.
His larger point is easier to understand. People sometimes become so familiar with stress that they stop recognizing how much of it they are carrying.
Leaving Work Does Not Automatically Fix Everything
Ronnie experienced relief, but another retiree may feel something very different.
A person who loves work may miss coworkers, responsibility, recognition, professional status, or the feeling of being needed.
Retirement can also create too much unstructured time. Someone whose social life existed mostly at work may suddenly feel isolated.
That is why retirement readiness needs more than a portfolio balance. Money matters, but so do routine, relationships, health insurance, purpose, and daily life.
| Area | Strong Position | Warning Sign |
|---|---|---|
| Basic spending | Income and withdrawals can cover realistic expenses | Plan requires constant spending cuts |
| Healthcare | Coverage is identified through age 65 and beyond | Plan assumes Medicare starts immediately |
| Social Security | Claiming ages have been compared | Benefit claimed only because work stopped |
| Cash reserve | Near term bills can be paid without forced selling | Market decline could create immediate problems |
| Debt | Payments fit comfortably inside retirement income | High fixed payments dominate the budget |
| Daily life | Interests and relationships exist outside work | Work provides almost all purpose and contact |
This table does not create a universal retirement score. It simply shows where a seemingly strong plan may still have weak spots.
Someone can be financially prepared but emotionally unprepared. Another person can be emotionally finished with work but financially exposed.
Simple Became Enough for Ronnie
Another major change happened in how Ronnie thought about freedom.
Before retirement, freedom seemed connected to having more. After retirement, it started looking more like quiet mornings, open afternoons, rest, nature, and time with his wife.
That shift can affect retirement spending. A person who no longer feels pressure to constantly upgrade may need less money than expected.
Consider a hypothetical household spending $90,000 a year while working. Some of that spending may be connected to commuting, work clothing, restaurant meals, and convenience costs.
If the household genuinely prefers a $70,000 retirement lifestyle, the income problem becomes smaller. The savings target may also become easier to support.
But simple living does not mean retirement is cheap. Housing, insurance, repairs, taxes, dental care, prescriptions, and long term care risks still exist.
The important difference is that lower spending comes from preference. It should not depend on denying normal needs or hoping nothing expensive ever happens.
Healthcare May Be the Hardest Part of Retiring at 61
For Americans retiring at 61, healthcare can become one of the largest immediate problems.
Medicare generally begins at 65. That means someone leaving work at 61 may need roughly four years of other coverage.
A retiree who loses employer health insurance may be able to use the Health Insurance Marketplace. Losing workplace coverage can create a Special Enrollment Period.
Premiums and subsidies depend on household income and other circumstances. That makes income planning especially important before Medicare begins.
Once Medicare starts, healthcare is still not free. In 2026, the standard Medicare Part B premium is $202.90 per month.
The 2026 Part B deductible is $283. The Part A inpatient hospital deductible is $1,736 per benefit period.
| Choice at 61 | Potential Benefit | Potential Cost | Best Fit |
|---|---|---|---|
| Leave work now | Immediate freedom | Must fund pre Medicare healthcare | Strong savings and insurance plan |
| Work longer | More earnings and employer coverage | Delays retirement | Job remains tolerable |
| Reduce hours | More freedom with some income | Benefits may change | Employer allows flexible work |
| Retire and use Marketplace | Separates insurance from job | Costs vary by income | Suitable Marketplace options available |
Healthcare should therefore be priced before a resignation letter is submitted.
A retirement plan can look strong until four years of insurance premiums and out of pocket costs are added.
Leaving at 61 Also Means Leaving a Strong Saving Window
There is another important 2026 issue for workers around Ronnie’s age.
The employee contribution limit for many workplace retirement plans is $24,500 in 2026.
Workers ages 60 through 63 can qualify for a larger catch up limit of $11,250. That creates an unusually valuable final saving period.
Someone who leaves work at 61 gives up the chance to keep making those salary deferrals. Employer contributions may disappear as well.
This does not mean money should always win. Staying in a miserable job purely to maximize a retirement account can have its own cost.
Still, the tradeoff deserves to be measured. Another year of work may add salary, employer health insurance, retirement contributions, and possibly pension credits.
A strong retirement decision compares those benefits with the personal value of leaving now.
The Identity Change Can Be Bigger Than the Money Change
Ronnie also describes retirement as an escape from constant professional performance.
There are no more performance reviews, supervisors to satisfy, office politics, or pressure to prove value to an employer.
For someone who disliked that environment, the change can feel freeing. But for someone who built identity around a profession, it can feel unsettling.
A retired teacher may no longer introduce herself as a teacher. A retired manager may suddenly lose the authority and responsibility that shaped daily life.
The answer is not always to replace a job with another packed schedule. Retirement does not have to become another performance contest.
Instead, identity can become broader. A person can be a spouse, friend, grandparent, volunteer, traveler, gardener, reader, mentor, or neighbor.
Ronnie’s story suggests that value does not disappear when employment ends. The measuring system simply changes.
Retirement Freedom Still Needs Other People
There is one danger in romanticizing escape from the rat race. Freedom can become isolation if work provided most of someone’s human contact.
The National Institute on Aging notes that retirement is one major life transition that can contribute to social isolation for some older adults.
Living alone does not automatically mean loneliness. Likewise, someone surrounded by people can still feel lonely.
Ronnie appears to have an important protective factor in his daily life. He shares routines, meals, mornings, and time with his wife.
Another retiree may need to build connection more deliberately. Clubs, volunteering, faith communities, classes, family contact, or regular time with friends can matter.
The point is not to stay busy every minute. It is to make sure freedom still includes people.
“Enough” Has an Emotional Meaning and a Financial Meaning
Ronnie says he is content with what he has. That may be one of the most important parts of his retirement philosophy.
But there are two meanings of enough. Emotional enough means no longer needing constant consumption to feel successful.
Financial enough means income and assets can reasonably support spending, healthcare, taxes, and unexpected costs.
A successful retirement plan needs both.
Consider a hypothetical 61 year old household needing $68,000 after tax each year. The question is not whether the household has hit an impressive round number.
The better question is where that $68,000 will come from before and after Social Security begins.
Cash, taxable investments, retirement accounts, pensions, part time income, and future Social Security may all play different roles.
The household also needs to consider what happens during a bad market early in retirement. Large withdrawals during a downturn can damage a portfolio.
Simplicity can help because every permanent expense removed from the budget reduces the income future assets must produce.
But the plan should still survive ordinary surprises. A roof repair, higher insurance premium, or medical bill should not immediately break it.
Social Security and Retirement Are Two Different Decisions
One common mistake is treating the date someone quits work as the date Social Security should begin.
Those are separate decisions.
Ronnie can leave work at 61 without receiving a regular Social Security retirement benefit. At 62, however, a new decision becomes available.
For people born in 1960 or later, claiming at 62 can reduce the monthly benefit by as much as 30% compared with waiting until FRA at 67.
Waiting beyond FRA can increase the worker benefit until age 70.
That does not make delaying automatically correct. Health, longevity, cash flow, survivor planning, and household needs all matter.
The stronger position is having enough flexibility to choose a claiming age deliberately. A cash shortage should not be the only reason a household claims early.
Early Retirement Can Create a Tax Planning Window
Leaving a high earning job can create years when taxable income is lower than it was during a career.
Those years can sometimes create useful tax planning opportunities before Social Security, Medicare income surcharges, and future required distributions become larger factors.
Roth conversions are one example. Whether they make sense depends on current tax rates, expected future rates, account balances, and Medicare considerations.
For 2026, the standard deduction is $16,100 for single filers and $32,200 for married couples filing jointly.
Someone age 61 does not yet qualify for deductions that require being at least 65 by the end of the tax year.
A person who is 61 in 2026 will also generally fall under the newer RMD rules that can push the applicable starting age to 75.
That may create a long planning window between retirement and required distributions.
Tax opportunities should still be modeled carefully. A strategy that lowers tax this year may create a different problem later.
Ronnie Did Not Lose Purpose. He Lost Pressure
This distinction may explain why Ronnie’s retirement did not feel empty.
He did not describe replacing work with another full schedule. He described finding value in ordinary experiences that had once been crowded out.
Cooking breakfast mattered. Being outdoors mattered. Time with his wife mattered.
Those things would never appear on a performance review. That is exactly why they feel different.
For some retirees, purpose becomes less public after work. It can move away from achievements and closer to relationships, interests, routines, and personal choice.
That will not happen automatically for everyone. Some people may need time to discover what makes retirement days feel meaningful.
But purpose does not have to resemble a career. It only needs to give someone enough reason to care about tomorrow.
What Someone Thinking About Leaving at 61 Should Review
Ronnie’s experience makes one point very clear. The cost of staying in a draining job is real, even though it is difficult to place on a spreadsheet.
The cost of leaving is also real. A strong decision needs both sides.
Instead of asking whether retirement simply “feels possible,” a 61 year old can turn the decision into specific dates and numbers.
| Priority | What to Review | Next Step |
|---|---|---|
| 1 | Annual spending | Build a realistic after tax budget |
| 2 | Healthcare | Price coverage through age 65 |
| 3 | Social Security | Compare benefits at 62, FRA, and 70 |
| 4 | Bridge assets | Decide what pays bills before benefits begin |
| 5 | Market risk | Test how the plan handles an early downturn |
| 6 | Taxes | Estimate taxable income for early retirement years |
| 7 | Daily life | Decide what replaces work structure and contact |
| 8 | Household plans | Discuss spending, travel, and time with a spouse |
One calculation can be especially useful. Estimate what one additional year of work actually adds after taxes and work related costs.
Then compare that amount with what another year of personal time means to you.
For one household, another year of work may greatly improve retirement safety. For another, it may add little financial security while costing a year the person values much more.





